

Nvidia (NVDA) has promised suppliers $390 billion for parts, sized for sales that would have to grow about 75% in fiscal 2028. The customers meant to buy those chips are taking longer to pay, and Nvidia is rationing the financing that helped them buy.
The Jensen Huang-founded Nvidia lost 25% of its value in the month before Tuesday’s results, in a slide that began before Huang resigned on November 11. The company then reported revenue of $115.844 billion against a forecast of about $109 billion and raised its outlook. Traders sold a gain of almost 3% straight back, so a record quarter bought the shares less than one session.
Nobody doubted the quarter. What the filings released alongside it put in doubt is the year ahead. Nvidia has signed for the parts to build a far bigger business, while its customers take longer to pay for the chips they already have. Traders are waiting to see who pays for the next lot, and a revenue number can’t tell them.
The parts are ordered whether or not the buyers show up
Nvidia’s commitments to its suppliers rose to $390 billion on October 25 from $279 billion three months earlier. The company says most of the increase is memory chips bought years ahead, and $203 billion of the total falls due in fiscal 2028, the year that runs to January 2028. Memory is the part Interim Chief Executive Officer Colette Kress blamed in August for squeezing margins, and Nvidia has now signed for far more of it.
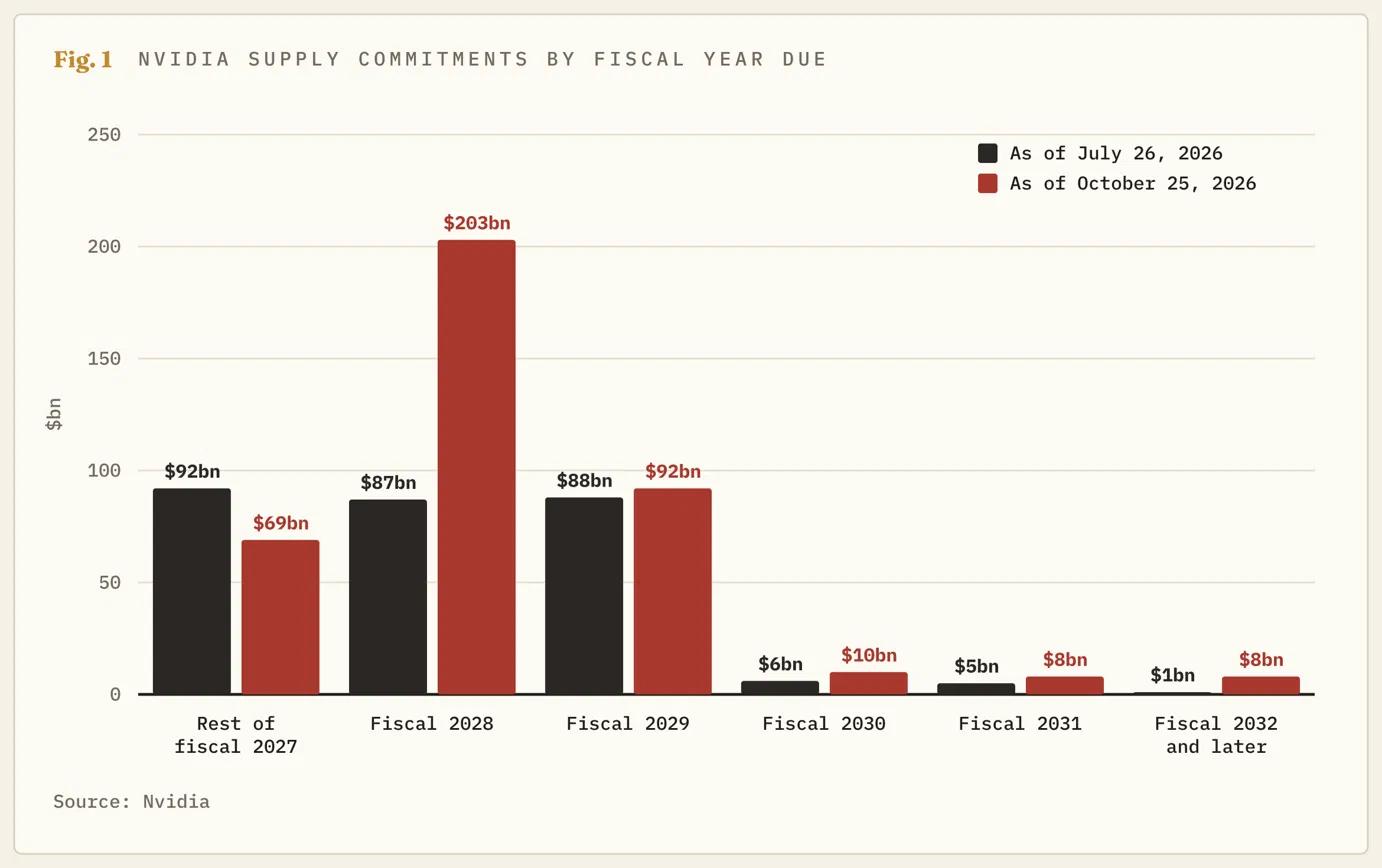
To see what the $203 billion assumes, start with Kress’s own target. She told analysts on Tuesday that revenue should grow approximately 75% in fiscal 2028. Nine months of reported sales plus her $130 billion forecast for the current quarter put fiscal 2027 near $424 billion, so the target works out to roughly $741 billion. She expects to keep 72%-73% of each sale after the cost of making the chips, which would put that cost at 200-208 billion.
From there, the risk runs one way, because parts bought in time for a 75% year are too many for anything less. If sales grow 50% instead, Nvidia would likely be left holding parts for chips nobody ordered, since nothing in the commentary says the bill shrinks when the orders do. Its raw materials inventory has already quadrupled to $15.802 billion from $3.807 billion in January. The $203 billion is a contract, and the 75% came with the word approximately attached.
The forecast has fourteen weeks in it
Before that target comes the current quarter, where the $130 billion forecast beat the roughly $125 billion analysts had pencilled in. It looks like 12% growth on the quarter just reported, but Nvidia’s calendar gives this quarter 14 weeks in place of the usual 13. Per week, the forecast is about 4% higher, against the 20% growth Nvidia just reported. Kress beat her last forecast by 7%, so the real number will likely be higher. Even so, reaching $741 billion from a 13-week pace near $121 billion would require about 18% growth in each of the next four quarters. The 12% and the 4% are the same forecast, and the only difference is whether the extra week counts.
Most of the new sales haven’t been paid for
Nvidia’s customers took an average of 64 days to pay in the quarter, up from 60 the quarter before and 51 in January, on the measure known as days sales outstanding (DSO). Money owed by customers reached $81.033 billion, up $18.052 billion in a quarter when revenue grew by $19.623 billion. Two customers owe 35% of the total, or about $28 billion between them.
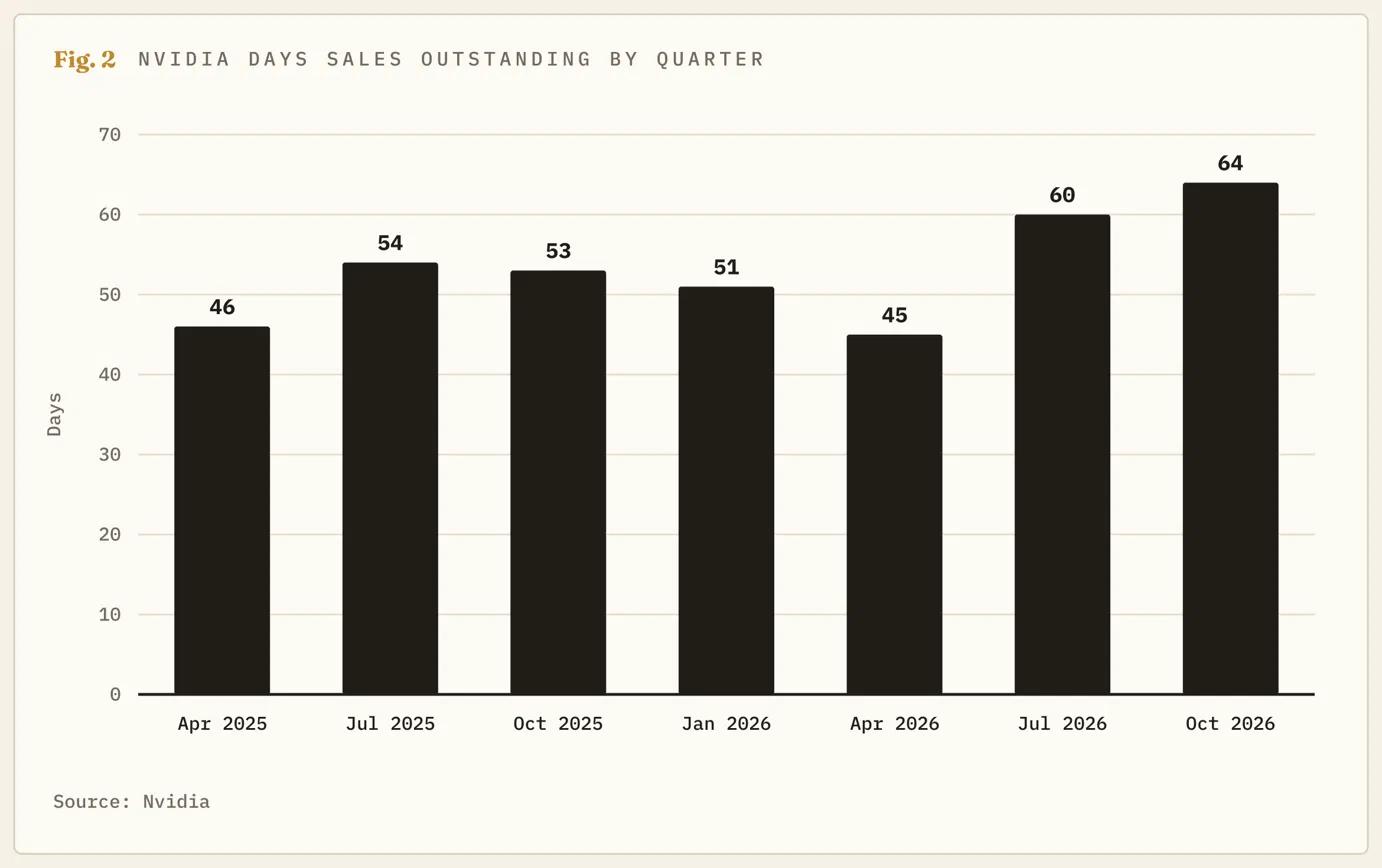
On that point, Nvidia’s explanation is the timing of its new Rubin shipments and longer terms for certain customers with investment-grade credit, meaning the strongest ratings. The same commentary says many of the smaller cloud firms renting out its chips, which it calls neoclouds, and many of the labs building the biggest artificial intelligence (AI) models are growing faster than their balance sheets can support. Nvidia vouches for the credit of the customers who owe it money in the same document that questions the credit of the fastest-growing ones.
For those customers, Nvidia has been part of the financing. Its guarantees, which promise payment if someone else defaults, rose to $118 billion from $108.5 billion. Of that, $105 billion stands behind an Ohio campus SB Energy is building for OpenAI, and SB Energy’s own share-sale filing says OpenAI isn’t an investment-grade tenant. The other $9.5 billion is new, and the commentary now lists hardware financing among the things Nvidia stands behind without saying whose hardware.
Under Kress, that help is getting harder to come by even as the guarantee total rises. She told analysts it would be disciplined and selective, and the amount pledged to neoclouds fell to $32 billion from $36 billion. New wording says some of it could be reduced or eliminated if those firms can’t raise their own money. If customers needed Nvidia’s help to buy this year’s chips, they would likely need more of it to buy 75% more, and the help is being rationed just as the parts bill arrives.
A chip designer with twenty years of rent
Alongside the guarantees, Nvidia has signed data centre leases of its own. In its July-quarter commentary, it listed $25 billion of leases that hadn’t started and a separate $20 billion signed for third parties, which it said it expected to hand on. This quarter, the separate line is gone and the leases that haven’t started total $74 billion, with terms of up to 20 years. The wording now says Nvidia may assign some of them. The company describes the space as room for its own research, and $63 billion of the rent falls due in fiscal 2032 or later, so it would still be owed if the buildout slowed. That is a long commitment for a company that designs chips and owns no chip factories.
The cash did turn up this quarter
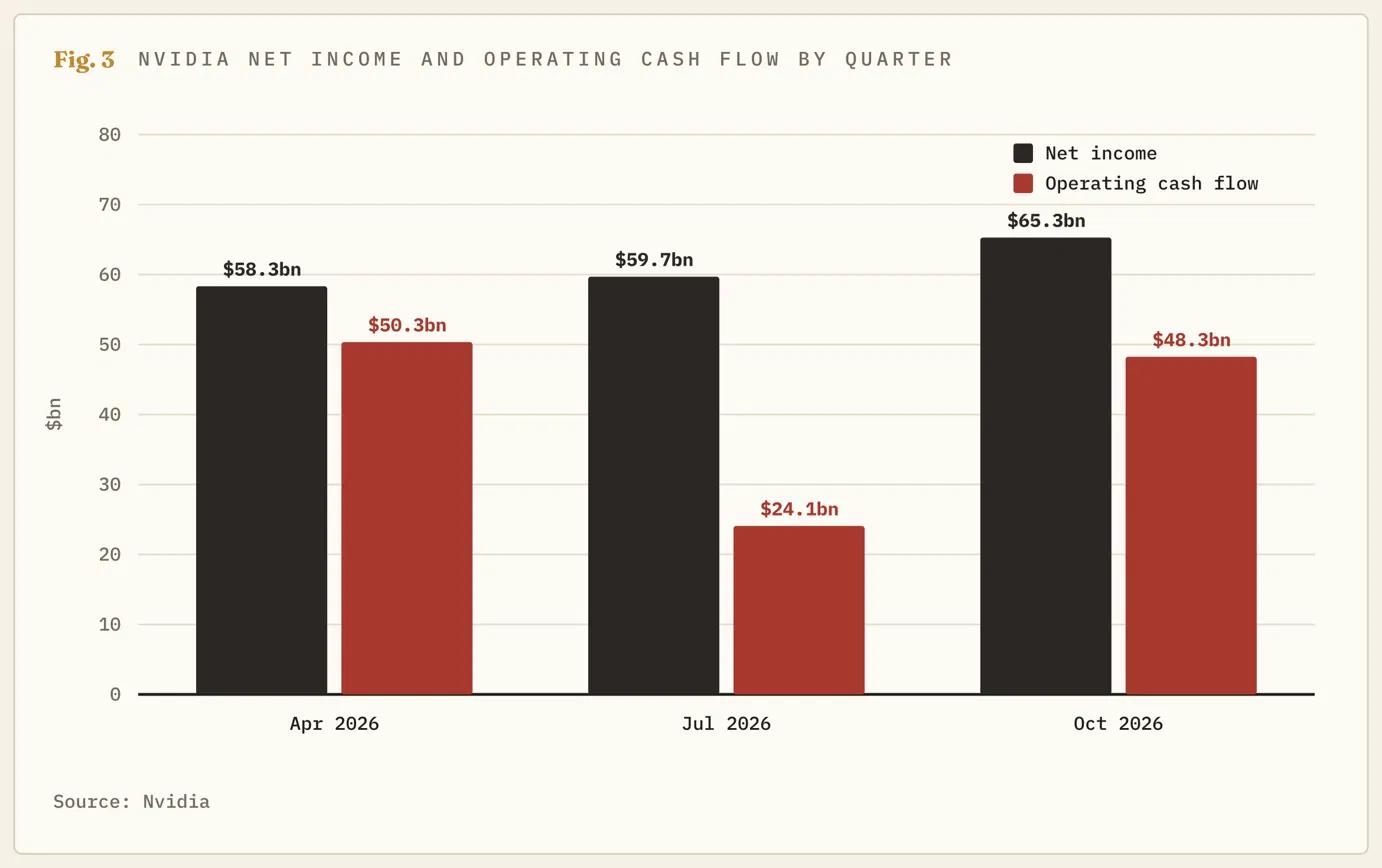
None of that has cost Nvidia anything yet, and the quarter’s cash was better than the one before. Operations brought in $48.253 billion against a profit of $65.287 billion, double the $24.077 billion of the previous quarter, although Nvidia says the timing of tax payments helped. Gains on its shareholdings added only $1.767 billion, down from $7.771 billion, so nearly all of the profit came from selling chips.
In the warehouse, the evidence points the same way. Chips ready to ship fell to $6.155 billion from $8.774 billion in January, so the inventory build is parts waiting to be assembled and not product waiting for a buyer. Nvidia hasn’t paid a dollar under any guarantee, and the first Ohio guarantee doesn’t take effect until fiscal 2029.
On that evidence, the customers are late and not absent, and the ones with longer terms are investment-grade by Nvidia’s account. A company that produced $43.777 billion of free cash flow, the cash left after capital spending, in three months can also afford to wait for a slow payer. It handed $28.1 billion to shareholders in the same quarter, which is not what a company worried about its bills usually does.
The market is waiting to see who pays
For now, the lean is against treating the beat as the all-clear, because the beat measures chips shipped and the open question is chips paid for. The first test is the full quarterly report, which Nvidia hasn’t yet filed. That report spells out the payment terms and financing arrangements that the results summary only names.
After that, the January quarter decides it. If days to pay fall back below 60, cash from operations catches up with profit, and the parts commitments stop climbing, the customers were only late. In that case, the bill is covered, and a 25% slide would look like a scandal discount on a business that is fine. If days to pay rise a third time and the commitments grow again, the lean hardens. Nvidia would then be funding both its suppliers’ bills and its customers’ credit, for a year it has promised will be 75% bigger.
Until one of those outcomes shows up in a filing, a rally would rest on revenue that hasn’t been collected. That is what traders declined to pay for after Tuesday’s results.
