

The answers often come down to details people only learn once a separation is underway, such as how the mortgage stress test applies when one name comes off the loan, or how the Home Buyers’ Plan works when a marriage ends.
Neil Drepaul, a mortgage broker, director and co-owner of Canadian Mortgage Services, answered 10 questions for MoneySense to work out those details.
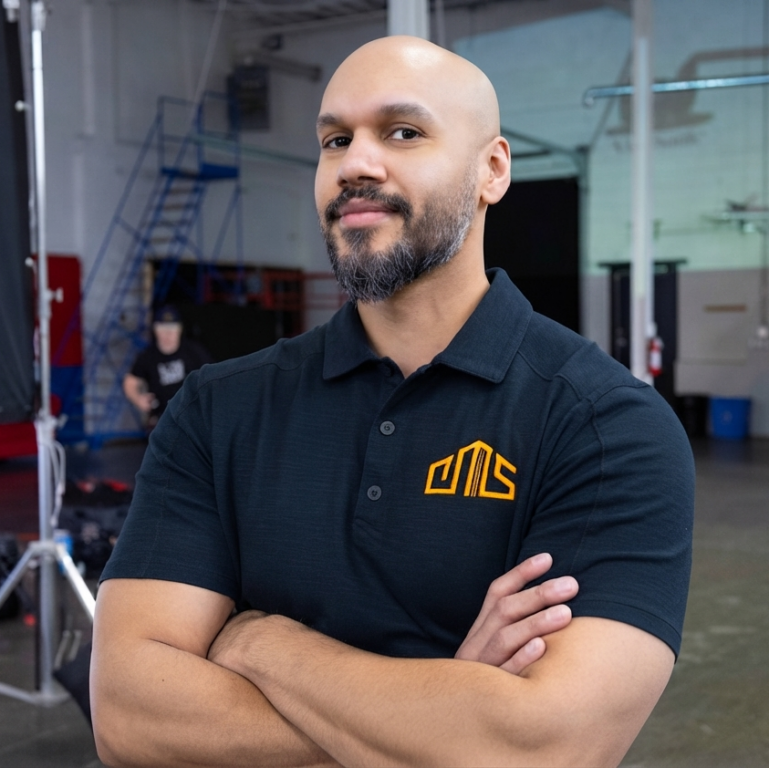
Drepaul has 14 years of experience in the Canadian mortgage and lending industry and works in the family business his father founded in 1988. His areas of expertise include mortgage rates and renewals, lending rules, self-employed borrowers, refinancing and debt consolidation, and the broader economic factors that can affect Canadians’ mortgages and access to credit.
Below, he explains how support payments count as income, what lenders need to remove an ex’s name, how a buyout works, and why a prepayment penalty and your mortgage renewal date matter when you plan your next move. His examples draw on Ontario’s rules, which differ from province to province, so double-check how your own province handles these situations. His guidance is not legal advice, and a family lawyer should work alongside your broker.
What should I do with my mortgage when I get divorced?
What’s the very first mortgage-related step someone should take when they decide to divorce, before lawyers or realtors even get involved?
Decide who is staying and who is leaving. Every other decision follows from that answer. The mortgage does not care who was right. It only wants to know whose name is staying on it.
The first step is for the person staying to find out whether they can carry the mortgage alone. Two incomes qualified for this house the way two people carry a couch up a staircase. Before either of you let go, find out whether one person can hold the weight alone. If not, you may end up like the famous “pivot” scene in Friends where the couch gets cut in half.
A broker can tell the person staying within a few days what they qualify for on their own, and that number shapes what the lawyers negotiate. The smoothest files I see are those where the lawyer, broker and realtor (where applicable) are talking to each other early.
Before that first call, pull together four things: your latest mortgage statement, your renewal date, a realistic value for the home, and a list of every debt with both names on it. And keep every joint payment on time while you sort it out.
One thing to know before you move out. In Ontario, a married couple’s home is the matrimonial home, and both spouses have an equal right to live in it no matter whose name is on the title. Neither can sell it or borrow against it without the other’s written consent. Common-law couples get no such protection here, and the rules differ by province. If you were never married and your name is not on the title, you have far less standing than you might assume. Legally, you are closer to a long-term guest than a co-owner.
Does spousal or child support count as income for a mortgage in Canada?
Can spousal or child support actually count as income when someone is trying to qualify for a mortgage on their own? Does it matter whether it’s in a signed separation agreement versus a verbal arrangement?
Yes, both can count, and in many files the numbers do not work favourably without them.
What matters is the paper. Lenders only use support that is written into a signed separation agreement or a court order. A verbal arrangement carries no weight with a bank, and it gives you very little protection either. No lender has ever accepted “he said he would” as a supporting document. In Ontario, for example, a separation agreement has to be written, signed and witnessed before it can be enforced.
Outside of this mandatory document, lenders will differ on policy. Some will work from a freshly signed agreement. Others want to see three to six months of deposits first. Therefore, ensure payments are made by bank transfer from day one, never cash, so there is a clean paper trail.,
Lenders also look at how long the support will last. Child support for a teenager will not carry the weight of child support for a six-year-old. Many lenders will count the Canada Child Benefit as well.
Lenders also cap how much of your qualifying income can come from support, often at a third to a half. In other words, qualifying income cannot be 100% support payments. Support is scaffolding, not a foundation. A lender will let it hold up part of the application, never the whole building. The Canada Child Benefit is usually capped too and only counts for children under the age of 12 (for standard five-year terms). So run the real numbers with a broker rather than assuming the full support amount counts.
One thing people overlook. If you are the one staying in the home and also the one paying child or spousal support, banks count it against you. It is either taken off your income or added to your debts.
How do I qualify for a mortgage on my own after divorce?
If the spouse keeping the house can’t qualify for the mortgage alone, what are their realistic options? A co-signer, a private lender, a longer amortization, or is selling really the only path?
A co-signer, a private lender, a longer amortization, or selling?
